Accelerating Financial Innovation With Ready Made Core Banking Infrastructure
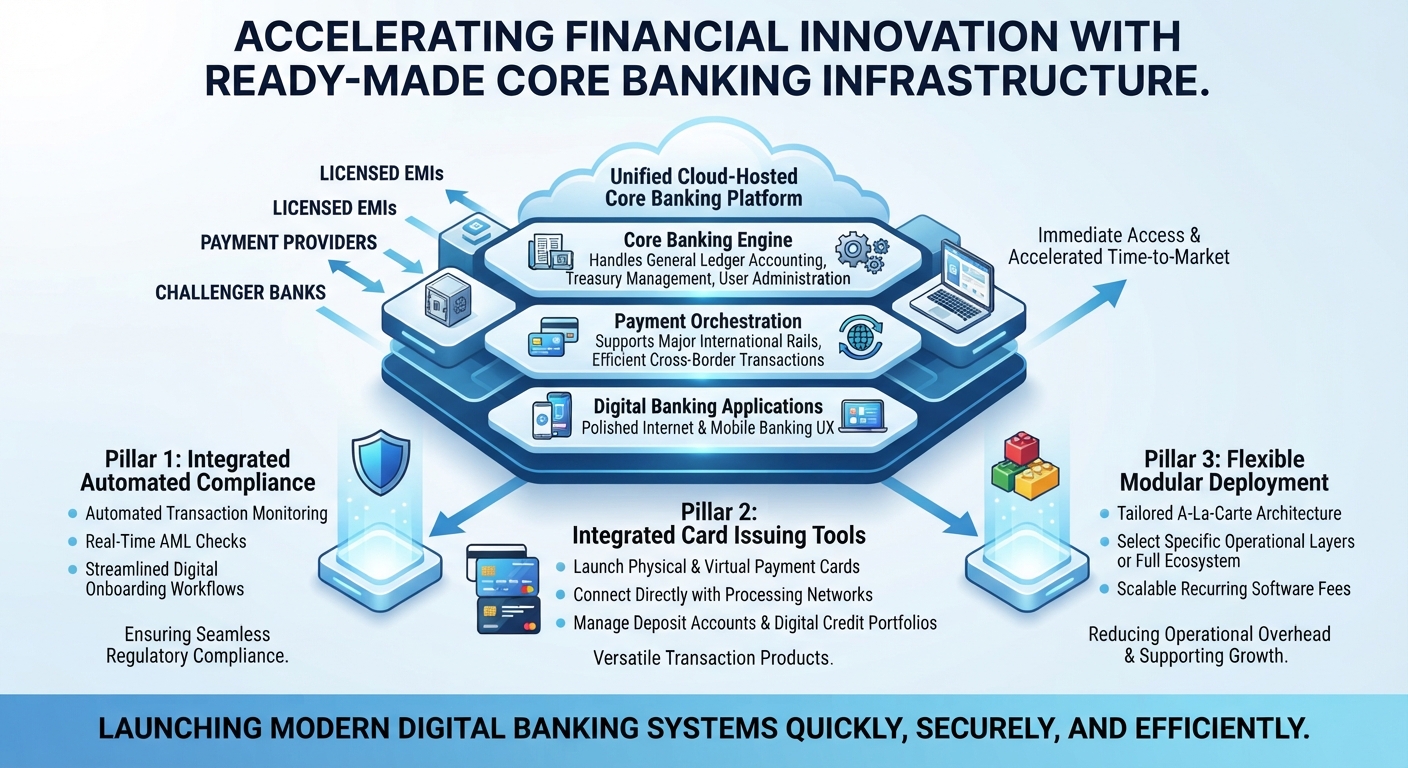
Launching or modernizing a digital financial institution no longer requires years of complex software development or prohibitive upfront capital expenditures. Through our trusted HPC partner network, licensed Electronic Money Institutions, payment providers, and challenger banks gain immediate access to a unified, cloud-hosted core banking platform designed to accelerate time to market while ensuring seamless regulatory compliance across international jurisdictions.
Building Modern Digital Banking Systems Quickly
Financial enterprises require flexible technology stacks that combine back office administration with robust payment capabilities. A comprehensive core banking engine handles general ledger accounting, treasury management, and user administration within a secure cloud environment. Seamless payment orchestration supports major international rails, enabling institutions to process cross-border transactions efficiently while delivering polished internet and mobile banking applications to their customers.
Integrating Automated Compliance and Card Issuing Tools
Operating a secure financial entity demands rigorous regulatory oversight alongside versatile transaction products. Built-in compliance suites provide automated transaction monitoring, real-time anti-money laundering checks, and streamlined digital onboarding workflows. Furthermore, integrated card issuance modules connect directly with processing networks, allowing institutions to launch physical and virtual payment cards while managing deposit accounts and digital credit portfolios effortlessly.
Selecting Flexible Modular Deployment Options
Financial institutions benefit greatly from tailored a-la-carte architecture rather than rigid, monolithic software packages. Organizations can select specific operational layers or deploy an entire digital banking ecosystem matched directly to their business model. Flexible commercial structures combine fixed setup arrangements with scalable recurring software fees, reducing operational overhead while supporting rapid growth from startup operations to full enterprise stacks.
Frequently Asked Questions for Financial Institutions
1. How can traditional banks in Kenya modernize their core infrastructure quickly?
Financial institutions in Kenya can deploy a ready-made, cloud-hosted core banking SaaS platform that integrates directly with existing legacy systems.
2. What modular components are included in the core banking architecture for Kenya firms?
The platform offers an a-la-carte selection covering general ledger accounting, treasury management, back-office administration, and user management tailored for Kenya operations.
3. How do payment orchestration features support international and domestic transactions in Kenya?
The system supports major payment rails including SEPA, SWIFT, TARGET2, Visa B2B Connect, and Mastercard Move for seamless cross-border transfers alongside domestic clearing networks in Kenya.
4. What digital front-end suites are provided for retail bank customers across Kenya?
Institutions in Kenya receive pre-built internet banking portals and native mobile applications designed for rapid customer deployment.
5. How does automated compliance tooling protect financial institutions regulated in Kenya?
Built-in compliance modules provide real-time transaction monitoring, automated anti-money laundering checks, and digital onboarding verification aligned with Kenya standards.
6. Can challenger banks in Kenya issue physical and virtual payment cards?
Yes, dedicated card issuing modules connect directly with processing centres to enable immediate physical and virtual card creation for customers in Kenya.
7. What loan and deposit management features are available for Kenya lenders?
Specialized modules handle digital credit products, interest calculations, savings accounts, and term deposit management effortlessly across Kenya.
8. How do commercial pricing structures support growing fintech companies in Kenya?
Flexible commercial models combine fixed setup arrangements with scalable recurring software fees to match enterprise growth stages for firms in Kenya.
9. Are these core banking solutions compliant with regulatory frameworks in Kenya?
The universal, jurisdiction-agnostic architecture adapts easily to meet local regulatory requirements, data residency mandates, and compliance standards across Kenya.
10. How long does it take to deploy a ready-made digital banking platform in Kenya?
Deployment timelines in Kenya are significantly shorter than traditional software builds, allowing institutions to launch products in a fraction of usual timeframes.
11. What types of financial entities in Kenya benefit most from this modular platform?
Licensed Electronic Money Institutions (EMIs), Payment Institutions (PIs), retail banks, commercial lenders, and neobanks in Kenya utilize the platform to scale operations.
12. How does cloud-hosted infrastructure reduce internal technology overhead for organizations in Kenya?
Hosting core operations in the cloud eliminates the need for expensive on-premise server maintenance and internal hardware management teams across Kenya.
13. Can financial groups in Kenya upgrade specific legacy layers without a total system overhaul?
Yes, the modular a-la-carte design allows institutions in Kenya to replace single operational layers while keeping stable legacy components intact.
14. What security protocols safeguard sensitive customer financial data in Kenya?
Enterprise-grade encryption, zero-trust architectures, and multi-factor authentication protect all transactional data within the cloud environment for entities in Kenya.
15. How do digital onboarding tools improve customer conversion rates in Kenya?
Streamlined electronic know-your-customer workflows verify user identities instantly, reducing friction during the account opening process for users in Kenya.
16. What support is provided during the initial platform integration phase in Kenya?
Dedicated technical specialists guide financial institutions in Kenya through architecture mapping, parameter setup, and thorough system testing.
17. How do institutions in Kenya manage multi-currency accounts within the core engine?
The general ledger and treasury modules support multi-currency holding, automated foreign exchange calculations, and real-time ledger updates for firms in Kenya.
18. Can neobanks in Kenya launch specialized lending products using this software?
Specialized credit management modules enable digital lenders in Kenya to disburse loans, track repayment schedules, and automate collections.
19. How are software updates and security patches handled in a SaaS model for Kenya clients?
Continuous background updates deliver new features and security enhancements without causing downtime for end users in Kenya.
20. What reporting tools are available for executive decision-makers in Kenya?
Comprehensive dashboard reporting tools generate real-time analytics on liquidity, transaction volumes, risk exposure, and profitability for leaders in Kenya.
21. How do payment institutions in Kenya handle high-frequency transaction loads?
Scalable cloud infrastructure automatically adjusts computing resources to handle peak transaction volumes without performance degradation for firms in Kenya.
22. What role do open banking APIs play in connecting third-party financial services in Kenya?
Robust application programming interfaces allow institutions in Kenya to integrate open banking features and external fintech partnerships seamlessly.
23. How does transaction monitoring prevent fraudulent account activities in Kenya?
Automated rule engines flag suspicious transaction patterns in real time, alerting compliance officers to potential security breaches across Kenya.
24. Can credit unions in Kenya adopt these ready-made banking solutions?
Credit unions and mutual societies in Kenya utilize the platform to modernize member services and introduce digital mobile banking apps.
25. What disaster recovery measures protect core banking data for entities in Kenya?
Automated daily backups, geo-redundant server replication, and failover protocols ensure continuous business continuity for operations in Kenya.
26. How do fee structures accommodate seasonal fluctuations in transaction volumes for Kenya firms?
Flexible SaaS pricing tiers allow institutions in Kenya to scale software costs relative to active user growth and transaction frequency.
27. What training is provided for internal bank staff using the new platform in Kenya?
Comprehensive user training programs and operational documentation prepare administrative teams in Kenya to manage day-to-day platform workflows.
28. How does the platform assist with anti-money laundering reporting requirements in Kenya?
Automated audit trails and regulatory reporting generators compile necessary documentation for supervisory authorities in Kenya effortlessly.
29. Can corporate banking clients in Kenya manage complex treasury workflows?
Corporate portals offer advanced liquidity management, batch payment processing, and multi-tier user permission controls for businesses in Kenya.
30. How do virtual sort codes and virtual accounts integrate with the core banking ledger in Kenya?
Virtual account generation modules allow businesses in Kenya to allocate unique payment references directly to individual customer sub-accounts.
31. What mechanisms prevent unauthorized administrative access to bank records in Kenya?
Role-based access controls and mandatory multi-factor authentication restrict sensitive ledger modifications to authorized personnel within Kenya.
32. How do financial startups in Kenya secure funding while utilizing cloud banking software?
Demonstrating a robust, scalable technology stack reassures institutional investors and venture capitalists during due diligence in Kenya.
33. Can retail banks in Kenya customize the user interface of mobile banking apps?
White-label mobile applications allow institutions in Kenya to apply proprietary brand themes, logos, and colour palettes.
34. How are interest rates and fee schedules configured within the core system for Kenya markets?
Administrative parameter tables enable financial officers in Kenya to update interest rates, commission fees, and penalty charges instantly.
35. What automated reconciliation tools simplify end-of-day accounting for institutions in Kenya?
Automated clearing house and payment gateway reconciliation tools match incoming and outgoing funds with minimal manual intervention in Kenya.
36. How do institutions in Kenya ensure compliance with data protection legislation?
Built-in data privacy controls support secure customer record management in accordance with regional privacy laws in Kenya.
37. Can regional banks in Kenya expand their service offerings across international borders?
Multi-jurisdictional architecture supports cross-border currency clearing and compliance adaptation for expanding institutions based in Kenya.
38. What hardware requirements are needed for bank employees in Kenya to use the platform?
Staff in Kenya require only standard secure web browsers and encrypted workstations to access cloud-hosted administrative portals.
39. How do automated credit scoring engines evaluate loan applicants in Kenya?
Integrated credit risk modules assess customer data and credit bureau histories to generate automated lending decisions for borrowers in Kenya.
40. What testing environments are available before launching live banking features in Kenya?
Sandbox environments allow technical teams in Kenya to test API integrations and simulate user workflows prior to public release.
41. How does cloud hosting reduce the total cost of technology ownership for firms in Kenya?
Eliminating physical server procurement, datacentre maintenance, and specialized hardware upgrades significantly lowers operating expenses across Kenya.
42. Can wealth management services be integrated into the digital platform for clients in Kenya?
Specialized modules support investment portfolio tracking, advisory fee collection, and asset management reporting for wealth managers in Kenya.
43. What communication channels are available for technical troubleshooting in Kenya?
24/7 technical support desks assist IT teams in Kenya with incident resolution, system monitoring, and performance tuning.
44. How do payment gateways connect with clearing systems in Kenya?
Direct API connectors link core payment engines with domestic clearing and settlement infrastructure in Kenya.
45. What metrics indicate successful digital banking platform adoption in Kenya?
Active monthly users, mobile app engagement rates, and low transaction failure percentages measure platform success for institutions in Kenya.
46. How are software customization requests handled for unique bank products in Kenya?
Professional services teams develop bespoke modules tailored to specific business logic requirements upon request for clients in Kenya.
47. What audit logs track internal user actions within the banking software in Kenya?
Immutable audit trails record every administrative login, account modification, and transaction approval for security reviews in Kenya.
48. How do financial institutions in Kenya migrate data from older legacy systems?
Structured data migration protocols extract, clean, and load historical customer and ledger data into the new cloud database for entities in Kenya.
49. What future-proofing benefits do cloud banking platforms offer institutions in Kenya?
Regular feature releases ensure that financial institutions in Kenya stay abreast of emerging payment technologies and digital trends.
50. How can banking executives in Kenya schedule a technical platform demonstration?
Institution leaders in Kenya can contact our advisory team directly to arrange a customized demonstration of the core banking platform.
Let’s start a conversation
Let’s find the right next step for you.
Share your questions and goals. Our team will help you explore the support and opportunities available.